
By Eddy Hood, Founding Partner of Ignite Spot Accounting
You have money in the bank, payroll is covered, and you're considering your next hire. But is that balance enough to move forward?
Your business should keep enough usable cash to meet its obligations, fund its chosen goals, and maintain a cushion for uncertainty. The right amount depends on your cash-flow forecast, required runway, and risk tolerance. Three to six months of expenses can start the conversation, but it cannot finish it.
When I'm advising an entrepreneur, I want to understand what we're trying to accomplish before I recommend a reserve target.
Why the three-to-six-month rule doesn't tell the whole story
A months-of-expenses target leaves out expected collections, payment timing, and the decisions ahead of you.
Two consulting firms with identical operating expenses might need different business cash reserves. One collects predictable monthly retainers. The other depends on large project payments that arrive unevenly. Add an expansion to either business, and the cash requirements change again.
Use the rule of thumb as a starting question. Then examine the cash your specific plan requires, including what happens if receipts arrive late.
Step 1: Decide what you're building cash reserves for
Start cash reserve planning by naming the goal your money needs to support.
You may be investing in employees, marketing, technology, or additional capacity. During that growth season, you might deliberately accept lower margins and thinner reserves while you build something larger.
In another season, you may want to strengthen your balance sheet, prepare for economic uncertainty, or get ready for an ownership transition. I describe that as “fattening up for winter.” You're accumulating cash because financial resilience is the priority.
Neither approach is inherently wrong. What concerns me is spending as though you're expanding while telling yourself you're building a cushion.
Write down your goal, its timeframe, and the cash balance you want to protect. That gives the financial plan a purpose.
Step 2: Calculate how much cash your business needs
Calculate your reserve requirement from expected cash receipts and payments, then test how long available funds can support the plan.
Find your cash-flow break-even point
Before deciding how much cash to keep in reserve, I want to know the business's cash-flow break-even point. In other words, how much cash needs to come in each month to cover the money going out?
That includes more than operating expenses. We also need to account for taxes, loan payments, equipment purchases, and distributions to owners. A business can show a profit on its income statement and still run short of cash.
An agency can record earned revenue before a client pays. That's one reason profit and cash flow differ. Show borrowing separately; loan proceeds can replenish cash without making operations self-funding.
Use your profit and loss statement to understand profitability, then forecast when money changes hands.
Identify usable cash and monthly net cash burn
Usable reserves are funds available for the purpose you're evaluating, rather than your total bank balance. Identify restricted money and cash committed to taxes, payroll, and other existing obligations before deciding what can fund expansion.
Keep those commitments in your forecast, but count each payment once. Don't subtract an obligation from starting cash and subtract it again as a future outflow.
Monthly net cash burn is the amount by which cash payments exceed cash receipts during a month. Growth spending may create planned burn before additional client payments arrive. That can be intentional, but it needs a budget, milestones, and a response if results fall behind.
Calculate cash runway and test the assumptions
Cash runway estimates how long available cash can sustain negative net cash flow.
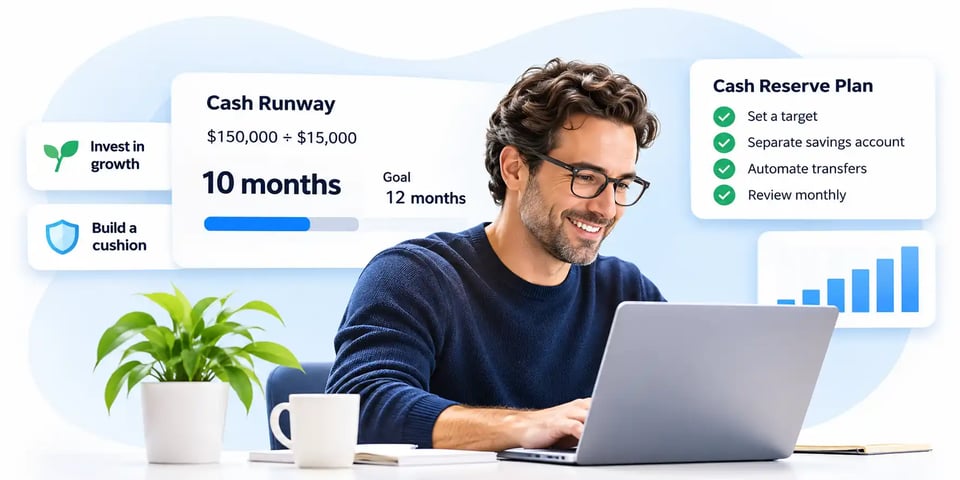
Cash runway in months = Available cash reserves ÷ Monthly net cash burn
This simplified estimate assumes reasonably stable burn. Consider this hypothetical expansion, using cash available after accounting for existing commitments:
| Financial measure | Amount |
|---|---|
| Available cash reserves | $150,000 |
| Monthly net cash burn during expansion | $15,000 |
| Estimated cash runway | 10 months |
| Entrepreneur's minimum comfortable runway | 12 months |
Now we have something meaningful to discuss. The business has 10 months of runway, but the entrepreneur isn't comfortable with anything less than 12.
That doesn't necessarily mean we abandon the growth plan. Maybe we delay a hire, reduce spending, or spend a few more months building reserves.
My job isn't to tell every entrepreneur how much risk to take. It's to help them understand the financial consequences of their decisions.
The 10 months is an estimate based on unchanged cash burn, not a guarantee or permission to spend down to zero.
I want to know when the investment should generate additional collected cash and what happens if that takes longer. Personal comfort cannot override the need to meet obligations as they come due.
If burn varies, use a month-by-month forecast. A 13-week cash-flow forecast adds near-term payment detail; extend the planning horizon for longer investments. Test delayed receipts and higher costs, and protect a minimum cash balance.
Knowing your runway turns an emotional decision into a measurable one.
Step 3: Build habits that grow your cash reserves
Build reserves through planned allocations and regular reviews rather than waiting to see what's left.
Open a separate business savings account
A separate account makes money reserved for a specific purpose easier to see and protect. Moving cash doesn't increase your total funds or make money surplus. Your forecast still determines what you can set aside.
Allocate a predetermined share of incoming cash
Choose a percentage of collections to transfer into savings, based on upcoming obligations and your reserve goal. Check that transfers leave enough operating cash to pay on time.
There's no universal savings rate. If your forecast cannot support the contribution needed, adjust spending, collections, the target date, or the plan itself.
Review progress at least monthly
Compare actual reserves with your target and explain any gap. Review cash generation, spending, and changed priorities before resetting transfers.
Without a deliberate system, reserve money can gradually disappear into everyday purchases. Consistent allocations give that money a defined destination.
When should you revisit your cash reserve target?
Revisit your target whenever revenue, operating costs, collections, growth plans, or personal goals materially change.
A slower-paying major client or a new hiring commitment can change your cash needs before the next monthly review. Update the forecast promptly, especially when available cash is tight.
Ask what changed, how it affects the lowest projected balance, and what decision follows. Cash-flow forecasting should inform the target instead of merely documenting it.
Frequently asked questions about business cash reserves
How much cash should a small business keep on hand?
Keep enough available cash to meet obligations, support planned investments, and provide a cushion for uncertainty. Small business cash reserves depend on collection timing, spending commitments, goals, and risk tolerance. A months-of-expenses benchmark cannot replace that analysis.
How do you calculate cash runway?
Divide available cash reserves by monthly net cash burn when burn is reasonably stable. The result estimates months until those funds are exhausted. If cash flow varies, forecast each month's balance and check payment dates rather than relying on an average.
Is it okay to use cash reserves to grow a business?
Yes, when spending is deliberate, forecasted, and compatible with meeting obligations. Identify when the investment should produce collected cash, test delays, and set spending limits or milestones. Growth plans need a response if assumptions don't hold.
Should business cash reserves be kept in a separate account?
I recommend a separate business savings account to distinguish reserves from everyday operating cash. Keep access appropriate for expected needs. The transfer organizes existing money; it doesn't create additional cash or remove obligations attached to it.
Build cash reserves around your business goals
There's no single cash reserve target that's right for every business.
Some entrepreneurs are investing in growth. Others are fattening up for winter. What matters is knowing which season you're in, how much cash your strategy requires, and whether you can comfortably support it.
Start with your goal. Calculate your runway. Then build the financial habits that will get you where you want to go.
If you'd like help connecting your reserve target to a financial plan, our fractional CFO team can work with you on cash planning, forecasting, and the trade-offs behind your next decision.