
By Eddy Hood, Founding Partner of Ignite Spot Accounting
Your team is busy, work keeps coming, and you're considering another employee. You want the help. You also want to know you can keep paying for it after the excitement of hiring wears off.
To determine whether you can afford a new employee, divide their full annual cost by your contribution margin. That tells you the additional sales needed to cover the hire. Then check whether the employee can help produce those sales and whether your cash can support the ramp-up.
When a client asks me about hiring, I calculate the additional revenue needed to cover the employee's full cost, then translate that target into monthly sales units. Then I ask: Will this employee help your business generate those additional sales and more?
I want a sales target we can evaluate, rather than a guess based on today's bank balance.
Why money in the bank doesn't settle the hiring decision
Cash in the bank can help fund a hire's first few paychecks. It doesn't prove your business can support the position over time.
Some of that money may already belong to upcoming taxes, vendor bills, or work customers paid for before you've delivered it. A strong collection month can also make the bank balance look healthier than your ongoing operations justify.
That distinction matters when profit and cash flow tell different stories. Before adding payroll, I want to understand your existing commitments and the earnings available after covering them. That means separating available hiring funds from money already committed elsewhere.
How much does an employee really cost?
The cost of hiring an employee starts with compensation, but salary alone leaves out part of the commitment. Estimate the full incremental cost your business will incur:
- Wages or salary, including expected overtime or bonuses.
- Employer payroll taxes and applicable employment insurance.
- Employer-paid health benefits and retirement contributions.
- Additional software, equipment, and workspace costs.
- Recruiting, onboarding, and training expenses.
I would put these costs into one itemized estimate using actual numbers for the role and your benefit plans. A universal salary multiplier can hide expenses that matter in your business.
Separate recurring annual costs from one-time hiring costs. Include relevant first-year expenses in the first-year analysis, and model their payment dates separately. Don't add paid leave twice if it's already included in annual salary; consider any additional coverage cost.
How to calculate the additional sales a hire requires
My approach starts with this formula:
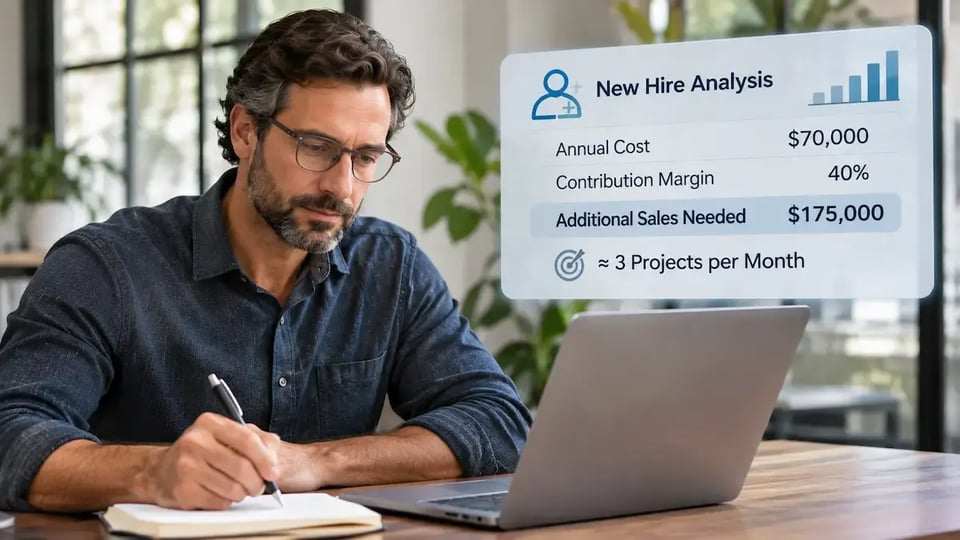
Additional annual sales required = Total annual employee cost ÷ Contribution margin percentage
Contribution margin is the percentage of each additional sales dollar remaining after variable costs are paid. Variable costs increase as you sell and deliver more work, such as project subcontractors or sales commissions.
At a 40% contribution margin, each additional dollar of sales leaves $0.40 to cover fixed overhead and profit. The other $0.60 pays variable costs.
For this illustrative hire:
$70,000 ÷ 0.40 = $175,000 in additional annual revenue
The $70,000 represents the employee's full incremental annual employment cost, including wages, employer payroll taxes, benefits, and relevant expenses. It is not necessarily their base salary.
| Hiring calculation | Amount |
|---|---|
| Annual employee cost | $70,000 |
| Contribution margin | 40% |
| Additional annual sales required | $175,000 |
| Average revenue per project | $5,000 |
| Additional projects per year | 35 |
| Additional projects per month | Approximately 3 |
This calculation assumes the employee is an additional fixed overhead expense and your contribution margin remains reasonably consistent. Don't also include that employee's cost in the variable costs used to calculate the margin.
For a billable hire who changes delivery costs or replaces contractors, model those changes separately. Review your profit and loss statement, but don't automatically substitute gross margin: accounting categories and variable costs may differ. Confirm which costs vary with sales before choosing your contribution margin.
The $175,000 covers the hire at break-even. It doesn't create additional profit. I want a good hire to help generate more value than their employment cost.
Turn the revenue target into monthly sales units
A $175,000 revenue target can feel abstract. I want to turn it into something you sell.
Assume your average project brings in $5,000:
$175,000 ÷ $5,000 = 35 additional projects annually
35 ÷ 12 = 2.92 additional projects monthly, or approximately three.
Now the question is concrete: Will this hire help your business sell and deliver roughly three additional projects a month, and more?
Those projects must be additional to the work already supporting your current expenses. For retainers, define the unit carefully: a $5,000 client-month and a $5,000 annual contract represent different amounts of work and revenue. Keep your revenue period and delivery costs consistent so the target translates into a service unit your team can plan around.
Will this employee help generate those additional sales?
The employee doesn't have to be a salesperson. But I want a credible connection between hiring them and improving the business's financial performance.
An agency delivery hire might create capacity for projects you're turning away. A consulting coordinator might free you to meet prospects. An IT account manager might help retain clients and expand existing relationships.
Each possibility needs evidence. Is there qualified demand? What work will the employee take over? How will you use the time you recover? Who owns the sales target?
Time saved doesn't automatically become revenue. Neither does an empty slot on the delivery calendar. Retention and cost savings can matter too, but quantify them separately rather than counting the same benefit twice. I would write down how the role will create value, the assumptions behind it, and when we'll review actual results.
Why cash flow timing can change the hiring decision
A favorable annual calculation doesn't guarantee money will be available on payday. Recruiting, equipment, and payroll may require cash before the employee's work produces customer payments.
I would add the hire to a 13-week cash flow forecast, then extend the forecast if the ramp-up or collection cycle runs longer.
Use realistic start dates, training time, billing schedules, and customer collection dates. Compare a reasonable case with slower sales or delayed payments. Check the lowest projected cash balance against your operating cushion, including payroll funding deadlines within each week. I want you to know how you'll fund the gap before making an offer, not after the first tight payroll.
Frequently asked questions about hiring costs
How much does it cost to hire an employee?
Add wages, employer payroll taxes, benefits, and incremental operating costs. Then include relevant recruiting and onboarding expenses for a first-year view. The total depends on the role and your business; base salary alone won't answer the question.
Can I afford to hire an employee without increasing sales?
Possibly, if existing sustainable earnings can absorb the full cost, or verified savings offset it. My additional-sales calculation shows what is needed when you want new contribution to cover the hire rather than reduce existing profit.
When should I hire an employee?
Hire when there's a defined need, a credible plan to fund the full cost, and enough cash to support the ramp-up. Being busy deserves attention, but review pricing, workload, and delivery processes before assuming another person is the answer.
How much does an employee cost at a 40% margin?
Employment cost and required sales are different numbers. In this example, a $70,000 annual employee cost requires $175,000 in additional annual sales at a 40% contribution margin. That covers the incremental hire, assuming other fixed costs stay unchanged.
Evaluate the numbers before making the offer
Before you hire, put four things on one page: full employee cost, required additional sales, monthly service units, and the cash needed before collections catch up.
Then come back to the question I ask when evaluating a hire: Will this employee help your business generate those additional sales and more?
If the answer depends on assumptions you haven't tested, investigate them before committing. Covering the employee at break-even gives you a starting point; I want the decision to strengthen your business beyond that.
If you'd like help working through the financial implications of hiring, Ignite Spot's fractional CFO services include cash forecasting, budgeting, and hiring-cost planning. We'd welcome a conversation about the role you're considering and what your numbers say.