Financial Literacy Guide for Kids
October 27, 2026 - Last updated by Eddy Hood
A child choosing between two snacks is already practicing a money skill: deciding how to use something limited. Financial literacy for kids starts with small choices like these, not complicated lessons.
Learning to manage money helps children plan, recognize trade-offs, and recover from mistakes. You can introduce each concept gradually, whether you are a parent, teacher, or caregiver. Start with coins and everyday choices, then build toward budgets, banking, and borrowing.
Keep conversations calm and practical. Children do not need to know every detail of household finances or feel responsible for adult bills. They need safe opportunities to practice.
Financial Literacy by Age Group
Use these age ranges as starting points, not deadlines. Adjust activities to each child’s experience and learning needs. Pretend money works well when real spending is not practical.
Ages 5–7: Recognize money and make choices
Learning goals: Identify common coins and bills, distinguish needs from wants, and understand that spending money leaves less for something else.
- Sort and count: Sort coins by type, name their values, and combine them to make a dollar. Supervise young children around coins.
- Choose within a limit: Offer a pretend $5 budget and several labeled items. Ask which combination fits and what must stay behind.
- Discuss needs and wants: Compare drinking water with a fancy water bottle. Explain that needs matter first, while wants can still be enjoyable.
Ages 8–10: Earn, save, and compare
Learning goals: Connect work with income, save toward a specific goal, make a simple budget, and compare prices.
- Build a savings tracker: For a $24 goal, saving $4 each week takes six weeks. Draw six boxes and color one after each deposit.
- Plan an earning task: Agree on an optional, age-appropriate job, payment, and completion standard before work begins. Keep ordinary household responsibilities separate if that suits your family.
- Compare purchases: Give a pretend snack budget and compare two options. Discuss price, quantity, and whether food might go to waste.
Ages 11–13: Manage money independently
Learning goals: Manage an allowance or gift money, track spending, understand bank accounts, and explore compound interest.
- Keep a two-week record: Write down money received, purchases, and the remaining balance. Review patterns without criticizing every choice.
- Compare accounts: With an adult, inspect two youth savings accounts for fees, access rules, and interest. Check whether adult involvement is required.
- Model compounding: At a hypothetical 5% yearly rate, $100 becomes $105 after one year and $110.25 after two, with annual compounding and no deposits or withdrawals. The second year’s interest includes interest on earlier interest; this is an illustration, not a promised rate.
Ages 14–18: Prepare for real expenses
Learning goals: Budget for responsibilities, read paychecks, understand taxes and debt, and save for longer-term goals.
- Budget actual costs: Use income or a fictional amount to plan transportation, phone costs, savings, and entertainment. Include an unexpected expense and revise the plan.
- Read a sample pay stub: Identify gross pay before deductions, tax withholding, and take-home pay. Explain that withholding goes toward taxes and is not necessarily the final tax owed.
- Compare payment choices: Discuss paying $100 now versus borrowing it. Identify repayment dates, interest, and fees before deciding.
- Plan beyond this month: Divide a larger goal, such as training or a vehicle, into monthly savings targets. Explain that investments can lose value, unlike the predictable arithmetic of a savings illustration.
Five Essential Money Skills Every Child Should Learn
Earning
Money can come from work, gifts, or an allowance. Help children distinguish these sources. A younger child might complete an agreed extra task; a teenager might compare hourly pay with transportation costs before accepting a job.
Saving
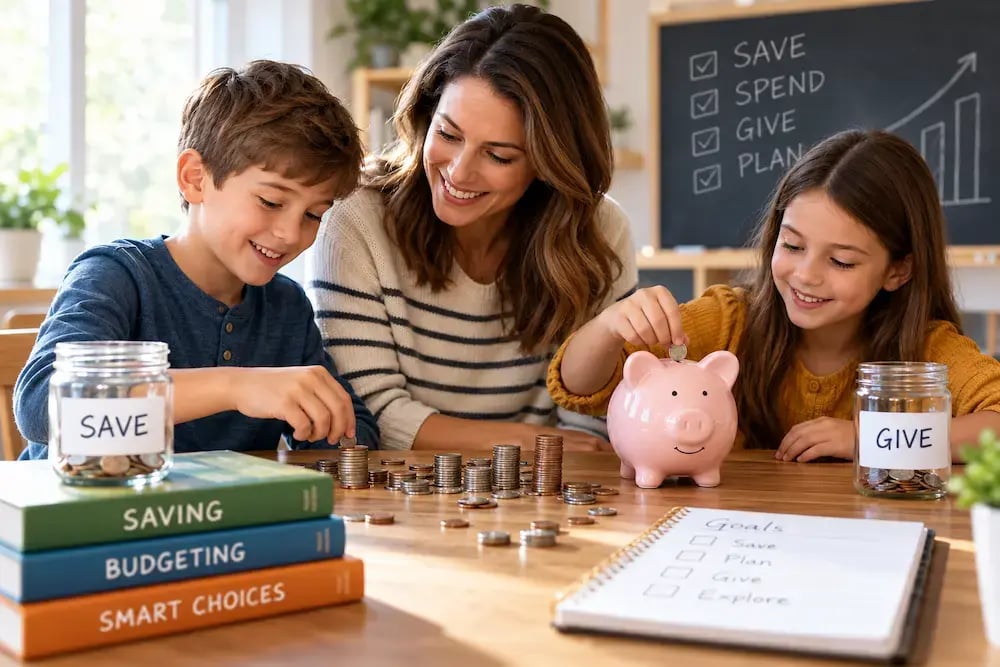
Saving means keeping money for later. Name the goal and separate that money from spending funds. A labeled jar works for younger children; an older child can maintain separate balances on paper or in an account.
Spending
Good spending means choosing deliberately, not avoiding every purchase. Before buying, ask: Do I want this enough to give up something else? Will I use it? Would waiting change my decision?
Budgeting
A budget is a plan for available money. For example, a child receiving $10 might assign $5 to spending, $4 to saving, and $1 to giving. The amounts should fit the child’s goals, not a rigid formula.
Giving
Giving connects money with personal values. Let children choose a cause and discuss how to check that an organization is legitimate. Donating time or useful items also counts; generosity does not require spending money.
Activities That Make Learning About Money Fun
These financial literacy activities for kids need little preparation:
- Open a pretend grocery store. Label pantry items with prices. Take turns shopping, counting payment, and checking change.
- Try a savings challenge. Choose a manageable amount to set aside each week. Celebrate consistent effort rather than who saves the most.
- Compare supermarket prices. Look at unit prices, such as cost per ounce. Ask whether a larger package is useful, not merely cheaper per unit.
- Plan a family outing. Set a spending limit and include transportation, food, and admission. Compare the plan with actual costs afterward.
- Play receipt detective. Find purchased items, discounts, and sales tax on a receipt. Check the total together.
- Make a wait-and-decide list. Write down a wanted purchase and revisit it after several days. Discuss whether it still feels worthwhile.
- Solve a surprise-expense scenario. Add a fictional bicycle repair to a sample budget. Ask what could change without borrowing.
When teaching kids about money, treat a disappointing small purchase as a conversation starter, not a character flaw.
How to Teach Kids About Banking, Credit, and Debt
Checking and savings accounts
A checking account holds money for everyday payments. A debit card usually takes money from that account; it does not create extra income. Track purchases and pending payments so the balance is not misleading.
A savings account keeps money for future goals and may pay interest. Compare fees and account terms with an adult before opening one.
Interest is money a bank may pay you for keeping savings there, or money a lender charges you for borrowing. Compound interest builds on both the starting amount and previously accumulated interest.
Credit cards and borrowing
A credit card lets you borrow from the card issuer. Borrowing is not earning or saving: borrowed money must be repaid, often with added costs. Debt is the amount you owe.
Read a sample statement together. Find the statement balance, minimum payment, due date, and annual percentage rate (APR), which describes the annual interest rate. Paying only the minimum can leave debt growing through interest.
For many cards, paying the full statement balance by the due date avoids interest on purchases when a grace period applies. Check the terms; cash advances and other transactions may work differently.
Before borrowing, ask: What is the total repayment cost? Where will the payments come from? What happens if income stops? Never share banking passwords or verification codes with someone requesting them unexpectedly.
Free Financial Literacy Resources for Kids
These official financial literacy resources offer a focused starting point:
- FDIC Money Smart for Young People: Free curricula for pre-K through grade 12, with educator guides, handouts, and parent/caregiver materials. Useful for structured lessons and practical home conversations.
- CFPB Youth Financial Education: K–12 classroom activities, teaching guidance, and links to parent resources. Helpful for connecting money lessons with other subjects.
- Federal Reserve Education: Free economics and personal finance lessons and activities for K–12 and beyond. Choose materials matched to the learner’s grade and topic.
- Jump$tart Coalition: A clearinghouse of financial education materials for students and adults, plus educator tools. Useful for finding age-appropriate options; check individual listings for cost and access requirements.
- Council for Economic Education’s EconEdLink: Free K–12 lessons, videos, games, and activities searchable by grade and topic. Helpful for teachers seeking ready-to-use classroom material.
A Simple Four-Week Financial Literacy Plan
Set aside about 15–20 minutes each week. Use real or pretend money.
- Week 1 — Choices: Sort five everyday items into needs and wants, then discuss one item that could belong in either category.
- Week 2 — Saving: Pick one goal, calculate how much to save weekly, and create a progress tracker.
- Week 3 — Budgeting: Plan a snack, outing, or fictional week of expenses within a fixed amount.
- Week 4 — Review: Compare the plan with what happened and choose one adjustment for next month.
Repeat with more independence as skills grow. Money management for kids develops through practice, not one perfect lesson.
Frequently Asked Questions
At what age should children start learning about money?
Begin when children show interest in shopping, counting, or making choices. Around age five, simple supervised activities can introduce money’s purpose.
Should children receive an allowance?
An allowance can provide practice, but it is optional. Explain what it covers and when it arrives. Pretend budgets or gift money can teach the same planning skills.
How can I teach my child to save money?
Choose a goal they care about, break it into manageable amounts, and make progress visible. Let them decide whether the goal still matters.
When should teenagers learn about credit cards?
Teach the basics before they can use one independently. Practice reading statements and calculating repayment costs without opening a card.
How can teachers introduce financial literacy in the classroom?
Use shopping math, fictional budgets, or stories about choices. Financial education for children should never require students to disclose household income or personal financial difficulties.